- PT
- EN
- FR
- DE
-
services
-
Contact
-
Credit Intermediation
-
Simulate
-
Guides & News
-
services
-
Contact
-
Credit Intermediation
-
Simulate
-
Guides & News
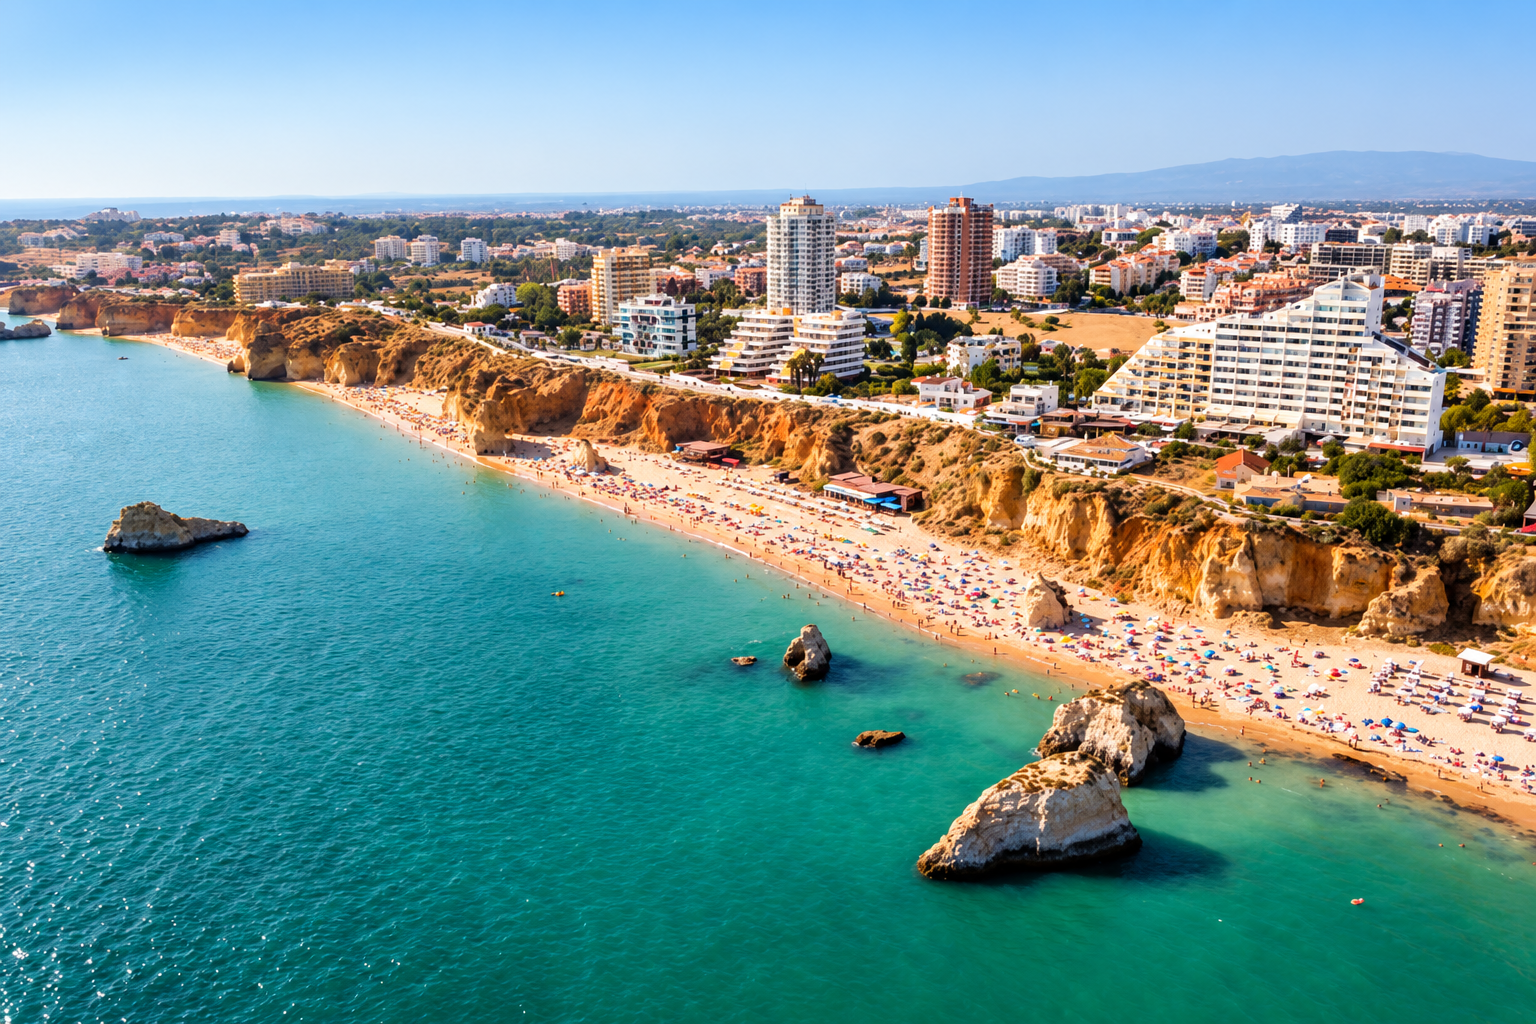
Mortgages in Portimão and the Algarve
Mortgages in Portimão and the Algarve
Mortgages in Portimão and the Algarve
Mortgages in Portimão and the Algarve
Looking to buy a home in Portimão or the Algarve and need a mortgage?
Objetivaquimera helps you prepare your mortgage application, organise your documents and understand offers from the lenders it works with.
Looking to buy a home in Portimão or the Algarve and need a mortgage?
Objetivaquimera helps you prepare your mortgage application, organise your documents and understand offers from the lenders it works with.
How does a mortgage work?
How does a mortgage work?
How does a mortgage work?
How does a mortgage work?
How does a mortgage work?
How does a mortgage work?
A mortgage helps finance the purchase of a home and is usually secured against the property. The loan is repaid in instalments that include principal and interest.
Before deciding, consider the deposit, the loan term, the type of interest rate and the associated costs. Approval and financing terms depend on the lender’s assessment.
For those buying their first home who want to understand the mortgage, the deposit needed and the costs involved before proceeding.
For those buying their first home who want to understand the mortgage, the deposit needed and the costs involved before proceeding.
Who could it be suitable for?
Who could it be suitable for?
Who could it be suitable for?
Who could it be suitable for?
For those planning to buy a new home who need to explore financing, taking into account existing financial commitments and the possible sale of their current home.
For those planning to buy a holiday home or a property for occasional use who want to assess financing, the deposit needed and the impact of additional expenses on their budget.
Buying your first home
Moving home
Moving home
Buying a second home
We review the applicants’ net income, its consistency and the supporting documents to understand their ability to afford the mortgage repayments.
We review the amount and regularity of all applicants’ monthly income to understand how the mortgage payment could fit into your budget and how much would remain for other expenses.
We review the amount and regularity of all applicants’ monthly income to understand how the mortgage payment could fit into your budget and how much would remain for other expenses.
What we assess
What we assess
We consider regular household expenses and existing loan repayments to assess the impact of a new mortgage payment on your budget.
We consider regular household expenses and existing loan repayments to assess the impact of a new mortgage payment on your budget.
We review the funds available for the deposit and the costs of buying and financing the property, including taxes, registration fees and other applicable expenses.
We review the funds available for the deposit and the costs of buying and financing the property, including taxes, registration fees and other applicable expenses.
We review the funds available for the deposit and the costs of buying and financing the property, including taxes, registration fees and other applicable expenses.
Income
Expenses
Own funds
Own funds
Own funds
Loan term
We review the requested loan term, the applicants’ ages and how the loan duration affects repayments and the total cost, taking lenders’ conditions into account.
We review the requested loan term, the applicants’ ages and how the loan duration affects repayments and the total cost, taking lenders’ conditions into account.
Employment situation
We review each applicant’s employment situation, employment contract or self-employed activity, and its continuity to understand their income and the documents needed for the application.
We review each applicant’s employment situation, employment contract or self-employed activity, and its continuity to understand their income and the documents needed for the application.
Credit commitments
We review the credit liabilities report provided by the applicants, including loans, credit cards and any loan guarantees, to understand their existing commitments.
We review the credit liabilities report provided by the applicants, including loans, credit cards and any loan guarantees, to understand their existing commitments.
Required documents
Required documents
Required documents
Required documents
Required documents
Required documents
You may be asked to provide:
• An identity document and Portuguese tax number (NIF);
• Proof of income, such as payslips or pension statements;
• An income tax return and assessment notice, or equivalent documents;
• Proof of employment or self-employment status;
• Recent bank statements;
• A credit liabilities report from Banco de Portugal.
Additional documents may be needed for self-employed applicants or those with income from abroad.
You may be asked to provide:
• An up-to-date property tax record (caderneta predial);
• A permanent land registry certificate;
• An energy performance certificate, where applicable;
• Documents relating to the property’s authorised use and planning status, as appropriate;
• A promissory purchase and sale agreement, if already signed.
The list is adapted to the property, the stage of the process and the lender’s requirements.
The documents requested depend on your circumstances and the lender. We explain what to gather at each stage.
The documents requested depend on your circumstances and the lender. We explain what to gather at each stage.
The documents requested depend on your circumstances and the lender. We explain what to gather at each stage.
The documents requested depend on your circumstances and the lender. We explain what to gather at each stage.
Applicants’ documents
Applicants’ documents
Property documents
Property documents
We discuss the home you want to buy, the financing you need and your current circumstances to identify the next steps.
We discuss the home you want to buy, the financing you need and your current circumstances to identify the next steps.
Steps in the process
Steps in the process
Steps in the process
Steps in the process
We explain which documents are needed and work with you to gather information about the applicants and the property, according to the stage you have reached.
We explain which documents are needed and work with you to gather information about the applicants and the property, according to the stage you have reached.
We review your income, expenses and available own funds to prepare the application and identify any points that need clarification.
We review your income, expenses and available own funds to prepare the application and identify any points that need clarification.
Initial contact
Initial contact
Gathering information
Gathering information
Reviewing your situation
Reviewing your situation
Submitting the application
Submitting the application
With your authorisation, we submit the application to the lenders we work with, as appropriate for your circumstances, and follow up on requests for additional information.
With your authorisation, we submit the application to the lenders we work with, as appropriate for your circumstances, and follow up on requests for additional information.
The bank’s decision
The bank’s decision
The bank assesses the application and decides whether to approve it and on what terms. We help you understand the response and, if an offer is made, explain its costs and conditions.
The bank assesses the application and decides whether to approve it and on what terms. We help you understand the response and, if an offer is made, explain its costs and conditions.
Support through to signing
Support through to signing
If you decide to proceed with an offer, we support you through the next steps until signing, coordinating the necessary documents and clarifications with you and the lender.
If you decide to proceed with an offer, we support you through the next steps until signing, coordinating the necessary documents and clarifications with you and the lender.
Frequently Asked Questions
Frequently Asked Questions
How much can I borrow for a mortgage?
The amount depends on your income, expenses, own funds, loan term and the property’s characteristics. The lender assesses your financial capacity and the property’s value before deciding. We can help prepare an initial assessment, but this does not constitute mortgage approval.
Is the monthly payment shown in the calculator final?
No. The calculator provides an estimate based on the information entered and the assumptions used. The actual monthly payment and other costs depend on the terms offered by the lender. A simulation is neither a contractual offer nor mortgage approval.
What is the difference between fixed, variable and mixed interest rates?
With a fixed rate, the interest rate remains unchanged throughout the loan term. A variable rate is reviewed periodically and generally consists of Euribor plus the lender’s margin, known as the spread. A mixed rate starts with a fixed-rate period, followed by a variable-rate period. The choice depends on your budget, your preference for predictability and the terms of each offer.
What should I compare in mortgage offers?
In addition to the monthly payment and spread, compare the rate type, loan term, annual percentage rate of charge (TAEG), total amount payable (MTIC), insurance, fees and associated products. Use the European Standardised Information Sheet (ESIS, known as FINE in Portugal) and compare offers for the same loan amount and term. A lower monthly payment does not necessarily mean a lower total cost.
Request a review of your situation
Leave your contact details so we can discuss a mortgage for your home.
Request a review of your situation
Leave your contact details so we can discuss a mortgage for your home.
Request a review of your situation
Leave your contact details so we can discuss a mortgage for your home.
Request a review of your situation
Leave your contact details so we can discuss a mortgage for your home.